

Loan teams are under a familiar squeeze: Win the deal or protect the margin. Most try to do both with a spreadsheet and a gut call. That works until the team grows, rates shift, and your board asks why Q3 spreads came in 40 basis points below target.
According to Abrigo, only 34% of financial institutions use internal profit measures to set loan prices. The other 66% are pricing by competitive feel, historical rate sheets, or individual judgment. That creates margin leakage you cannot see until it shows up in your quarterly numbers.
Loan pricing software replaces that guesswork with a repeatable decision system. It factors in borrower risk, cost of funds, relationship value, capital requirements, and your target return, so every loan officer works from the same model, not a different spreadsheet.
The question is which platform fits your lending motion. Commercial relationship profitability, consumer price optimization, mortgage rate workflows, and auto lending operations each require a different tool.
What's inside
This guide compares 11 loan pricing software options across banks, credit unions, mortgage lenders, auto lenders, and private lending teams. Items were selected based on their presence in the category and verified feature fit.
Selection criteria:
- Lending type fit (commercial, consumer, mortgage, auto, or private)
- Pricing analytics and scenario modeling depth
- Profitability methodology (ROE, ROA, relationship value, risk grade)
- Implementation and advisory support for financial institutions
- Reporting quality for committees, examiners, and board-level decisions
Pricing and G2 ratings reflect verified sources and are noted where data is unavailable.
TL;DR
- Best for commercial loan profitability: LoanPricingPRO suits community banks and credit unions that need relationship-level ROE analysis
- Best for risk-based pricing with documentation: Abrigo covers banks and credit unions that need examiner-ready pricing consistency
- Best for consumer lending optimization: Experian Loan Pricing Optimization Software fits lenders using price elasticity and analytical models
- Best for commercial relationship managers: PrecisionLender gives bankers real-time deal coaching during loan structuring
- Best for mortgage pricing workflows: Marksman (Mortech) starts at $400/month with clear tier pricing; PollyEx targets capital markets teams
- Best for auto lending operations: defi SOLUTIONS connects pricing to origination, servicing, and dealer channel workflows
- Best credit data input tool: iSoftpull supports soft-pull prequalification at $3.84 per bureau pull, plans from $99/month
What is loan pricing software?
Loan pricing software helps lenders calculate risk-adjusted, profitable loan pricing by factoring in borrower risk, funding costs, capital requirements, competitive rates, institutional targets, and relationship value.
It is not a loan origination system, a servicing platform, or a general analytics dashboard. Understanding the difference matters before you buy.
Core capabilities:
- Risk-based pricing: Adjusts rates and terms based on borrower credit profile, collateral, and risk grade
- Profitability and ROE analysis: Models return on equity and return on assets against cost of funds and capital allocation
- Scenario modeling: Shows how changes in rate, term, fees, or relationship assumptions shift the deal economics
- Relationship pricing: Incorporates deposits, cross-sell, and full relationship value alongside the loan itself
- Competitive pricing support: Benchmarks rates against market data to stay competitive without eroding margin
- Rate sheet and margin management: Manages pricing rules and exceptions at scale
- Portfolio and lender reporting: Tracks performance by lender, branch, product line, or customer segment
- Documentation for approval workflows: Produces audit-ready outputs for loan committees and examiners
- Pricing optimization for consumer lending: Applies price sensitivity and elasticity models to maximize portfolio-level profitability
Category distinctions worth knowing:
Loan origination software manages application intake, underwriting, approvals, and closing. Loan servicing software handles payment processing and account management after funding. Mortgage product and pricing engines focus on investor eligibility, rate comparisons, and lock workflows. Loan pricing software focuses on the profitability and risk decision before or during approval.
Some tools overlap these categories. Start with the pricing decision you need to improve, then match the tool to that job.
When to use loan pricing software
Standardize pricing decisions across lenders
Growing lending teams drift when every loan officer works from a different spreadsheet or set of assumptions. One rep prices to a 12% ROE target; another accepts 8% without realizing it. Loan pricing software puts everyone on the same model, so exceptions get flagged, not buried.
Protect margin while staying competitive
Rate pressure is real. But cutting rate without modeling cost of funds, borrower risk, and relationship deposits creates deals that look like wins at origination and losses at quarter end. A pricing system shows exactly where the floor is before the relationship manager says yes.
Model scenarios before approving exceptions
Most pricing exceptions fail because the team does not know what they are actually approving. Running a deal through scenario modeling, changing rate, term, fees, and risk grade, gives the committee a clear picture of the actual yield before a decision is made.
Loan pricing software comparison
The table below summarizes all 11 tools by lending type and key differentiator. Verify pricing and G2 ratings directly with each vendor before purchase, as enterprise financial software pricing changes and several tools in this category sell by quote.
| # | Product | Best for | Key differentiator | Pricing | G2 rating |
|---|---|---|---|---|---|
| 1 | LoanPricingPRO | Community banks, credit unions | Relationship-level commercial loan profitability | Custom pricing | N/A |
| 2 | Abrigo | Banks and credit unions | Risk-based pricing with committee documentation | Custom pricing | 4.6/5 |
| 3 | Experian Loan Pricing Optimization | Consumer lenders | Price elasticity and profit-based optimization | Custom pricing | 4.0/5 |
| 4 | PrecisionLender | Commercial relationship managers | Real-time deal coaching during loan structuring | Custom pricing | 4.5/5 |
| 5 | Baker Hill | Banks and credit unions | Lending platform with pricing and credit risk tools | Custom pricing | 4.0/5 |
| 6 | Mortech | Mortgage lenders and brokers | Mortgage product and pricing engine | Custom pricing | N/A |
| 7 | Marksman | Mortgage lenders | Integrated PPE with published tier pricing | From $400/month | N/A |
| 8 | PollyEx | Mortgage capital markets teams | AI-native loan pricing and capital markets workflows | Custom pricing | N/A |
| 9 | Margill Loan Manager | Private lenders, finance teams | Flexible loan management with amortization depth | Quote-based, 30-day trial | 4.8/5 |
| 10 | defi SOLUTIONS | Auto lenders | End-to-end auto lending and servicing operations | Custom pricing | 5.0/5 |
| 11 | iSoftpull | Lenders needing credit-pull workflows | Soft-pull prequalification for pricing inputs | From $99/month, $3.84/pull | N/A |
Best 11 loan pricing software for 2026
1. LoanPricingPRO
LoanPricingPRO is commercial loan pricing software from Forvis Mazars, built specifically for community banks and credit unions. The platform models profitability in real time by pulling together loans, deposits, related business accounts, and personal accounts into a single relationship view. That full-relationship visibility means a loan officer can see the actual ROE of a deal, not just the rate.
Best for: Community banks and credit unions that need commercial loan profitability and relationship pricing in one workflow.
Key features
- Real-time ROE analysis at the deal level
- Relationship-level pricing across loans, deposits, and business accounts
- Scenario comparison for rate, term, and fee combinations
- Portfolio profitability reporting by lender, branch, and product
- Loan officer performance and profitability reporting
Why choose LoanPricingPRO: It fits institutions where the relationship manager needs to price a deal while seeing the full borrower picture, not only the loan request. The reporting layer also helps leadership coach lenders on profitability discipline.
LoanPricingPRO pricing: LoanPricingPRO sells by quote through Forvis Mazars. Request a demo or seven-day trial directly on the product page. Expect the quote to factor in institution size, data feed setup, custom model configuration, and training scope.
2. Abrigo
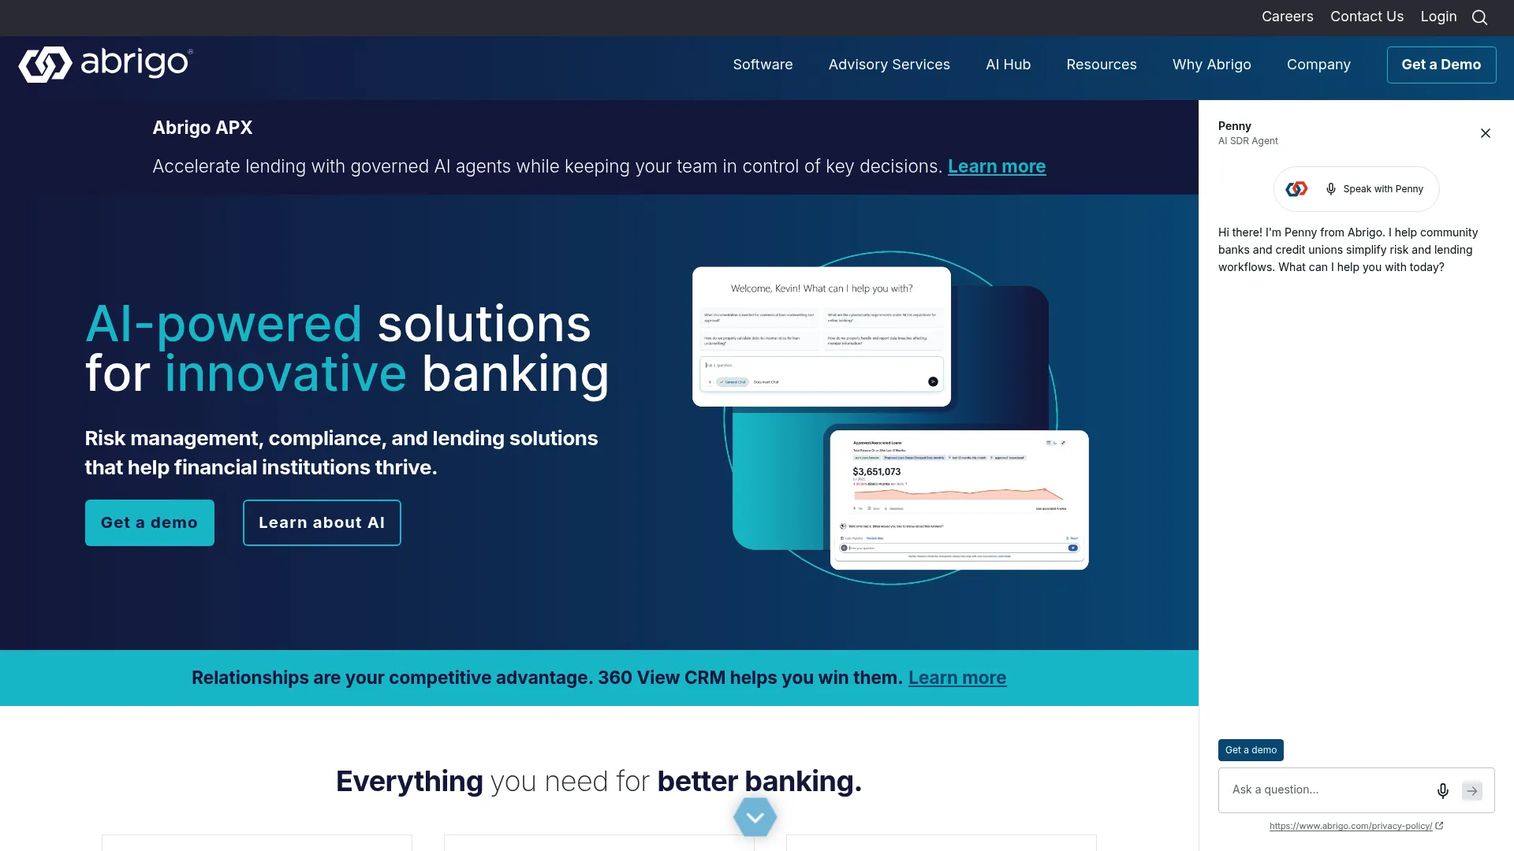
Abrigo delivers AI-powered software for financial institutions across lending, credit risk, compliance, and analytics. Its loan pricing capability sits within the broader Sageworks lending suite and centers on risk-based pricing tied to cost of funds, underwriting costs, borrower risk grades, and target ROE and ROA. The platform also generates documentation for loan committees and examiners, which matters in regulated lending environments.
Best for: Banks and credit unions that need consistent risk-based pricing and examiner-ready documentation for every lending decision.
Key features
- Risk-based pricing with cost factor modeling
- ROE and ROA target alignment
- Competitive pricing scenario analysis
- Funding, underwriting, and administration cost modeling
- Loan committee and examiner documentation outputs
Why choose Abrigo: It is the stronger fit when pricing discipline needs to be tied directly to credit risk methodology. Consulting and advisory support help institutions that need help building or validating their pricing model, not just deploying software.
Abrigo pricing: Abrigo prices by quote. The final figure reflects module scope, institution size, implementation services, and advisory needs. Contact Abrigo directly to start the conversation.
G2 rating: 4.6/5 (Abrigo Loan Origination, verified on G2)
3. Experian Loan Pricing Optimization Software
Experian Loan Pricing Optimization Software focuses on analytics-driven pricing for consumer and unsecured personal lending. Where commercial loan pricing tools center on relationship ROE, Experian's model adds price elasticity and customer response into the equation. The platform models how borrowers respond to different price points, then optimizes offers to balance profitability and portfolio growth simultaneously.
Best for: Consumer lenders that need personalized, analytics-driven pricing rather than a rate sheet or relationship profitability model.
Key features
- Risk and price-elasticity modeling
- Profit-based pricing optimization
- Personalized prices and terms at the customer or segment level
- Constraint-based optimization
- Portfolio growth analytics
Why choose Experian Loan Pricing Optimization Software: It fits when the pricing problem is not only credit risk but also consumer response. If your institution prices unsecured personal loans or consumer credit at volume, and wants to model price sensitivity, this platform provides analytical depth that commercial-focused tools do not.
Experian Loan Pricing Optimization Software pricing: Pricing requires a sales conversation with Experian. The final quote covers optimization scope, data inputs, portfolio complexity, and consulting engagement. Contact Experian Business Services for details.
G2 rating: 4.0/5
4. PrecisionLender
PrecisionLender is a sales and coaching platform for commercial banks that helps bankers structure, price, and negotiate more profitable deals. Its Andi virtual analyst provides real-time recommendations on deal structure and negotiation tactics as relationship managers build a deal. The platform also tracks pricing opportunities and performance by lender, region, state, or branch.
Best for: Commercial relationship managers who need pricing guidance and deal coaching during the structuring conversation, not after the deal is submitted.
Key features
- Real-time pricing insights and deal coaching via Andi virtual analyst
- Relationship Awareness for full relationship profitability analysis
- Risk-adjusted return analysis
- Pricing opportunity tracking by lender, region, and client
- Salesforce and Dynamics CRM connectors
Why choose PrecisionLender: The front-line use case is strong. Bankers get coaching before exceptions reach the approval stage, which means fewer low-yield approvals and better pricing consistency across the lending team.
PrecisionLender pricing: PrecisionLender sells by quote. Ask about user count, implementation requirements, data integrations, and commercial banking module configuration to scope the cost accurately.
G2 rating: 4.5/5 (verified on G2)
5. Baker Hill
Baker Hill provides configurable SaaS lending, loan origination, risk management, financial analysis, and relationship management solutions for banks and credit unions. Pricing and profitability analysis are included within the platform, but Baker Hill is not a standalone loan pricing calculator. It works best for institutions that want pricing context embedded inside a broader lending and risk workflow.
Best for: Banks and credit unions that want loan pricing tied to origination, credit risk, and portfolio monitoring in one platform.
Key features
- Commercial, small-business, and consumer loan origination
- Credit risk tools and portfolio monitoring
- Financial analysis and statement spreading
- Pricing and profitability analysis
- Digital applications and relationship management
Why choose Baker Hill: Choose it when the institution needs a broader lending platform rather than a dedicated pricing calculator. Verify that Baker Hill's pricing module meets your specific scenario modeling and documentation needs before committing.
Baker Hill pricing: Baker Hill states that pricing appears in the applicable order form. Contact Baker Hill for a scope-based quote.
G2 rating: 4.0/5
6. Mortech
Mortech provides mortgage pricing, product eligibility, APIs, online rate quoting, predictive analytics, and secondary marketing workflows for lenders. It is a mortgage-specific tool, not a commercial loan pricing platform. Mortgage lenders and brokers use it to search rates across investors, check product eligibility, compare pricing, and manage secondary market workflows.
Best for: Mortgage lenders and brokers that need real-time investor rate comparisons and product eligibility in a single workflow.
Key features
- Real-time mortgage pricing across multiple investors
- Product eligibility and automated investor guideline checks
- Online rate quoting with lead management integration
- Secondary marketing tools and historical pricing
- LOS integrations and mortgage APIs
Why choose Mortech: It fits mortgage-specific pricing problems: Product eligibility, investor rate comparisons, and speed to quote. It does not address commercial borrower relationship profitability.
Mortech pricing: Mortech's pricing requires a sales conversation. Contact Mortech to request pricing by user count, lender network access, and integration needs.
7. Marksman
Marksman is Mortech's branded mortgage pricing, eligibility, lead management, and secondary marketing software. It operates on the same platform but with published tier pricing that makes it easier to evaluate upfront. Online Quoting includes auto-quoting, one lead source, CRM and LMS, and email marketing. Higher tiers add the full mortgage pricing engine, multiple lead sources, rate tracking, LOS integration, lock pipeline management, historical pricing, and hedging integrations.
Best for: Mortgage lenders that want a clearly tiered mortgage pricing workflow with a known entry price before entering a sales conversation.
Key features
- Real-time mortgage pricing across investors
- Automated product and investor eligibility checks
- Lead management, distribution, and email marketing
- Lock pipeline management and historical pricing
- LOS integrations and hedging workflow support
Why choose Marksman: The published tier structure gives you a cost anchor before talking to sales. If your team needs the full PPE and secondary market capability, the Professional and Secondary tiers are quoted separately, but the Online Quoting tier at $400/month tells you whether Mortech's ecosystem fits your workflow before committing.
Marksman pricing: Online Quoting starts at $400/month. Professional and Secondary tiers are priced by quote. Ask about loan volume, investor connections, and LOS integration requirements when scoping.
8. PollyEx
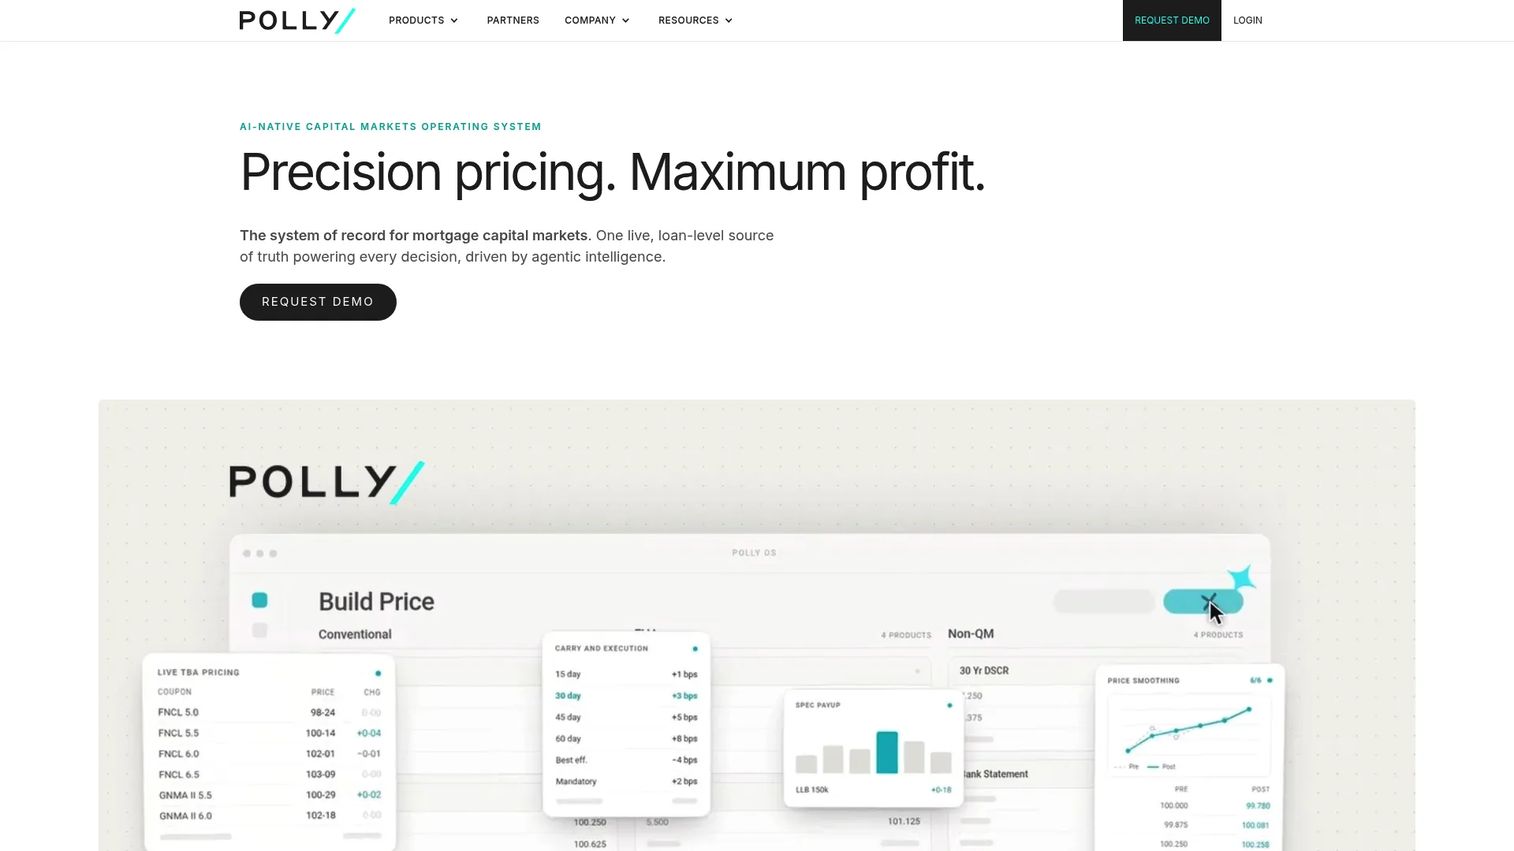
PollyEx (Polly) is an AI-native capital markets operating system for mortgage lenders. It covers loan pricing and eligibility, loan-level margin management, lock lifecycle automation, and no-code rule configuration. The version control and historical pricing analysis capabilities set it apart for capital markets teams that need to track pricing decisions over time and audit margin attribution across the loan pipeline.
Best for: Mortgage capital markets teams managing loan pricing, execution, margin attribution, and secondary market workflows.
Key features
- Product, pricing, and eligibility engine
- Loan-level margin management and attribution
- AI-powered lock lifecycle automation
- No-code rule configuration and version control
- API integrations with LOS, POS, CRM, and secondary systems
Why choose PollyEx: It fits capital markets teams where the pricing problem is execution and margin management, not front-end borrower qualification. If your team needs to track how pricing decisions affect margin at the loan level, Polly's attribution layer provides that visibility.
PollyEx pricing: Polly sells by quote. The website directs prospects to request a demo. Ask about transaction volume, module scope, investor connectivity, and integration requirements when scoping.
9. Margill Loan Manager
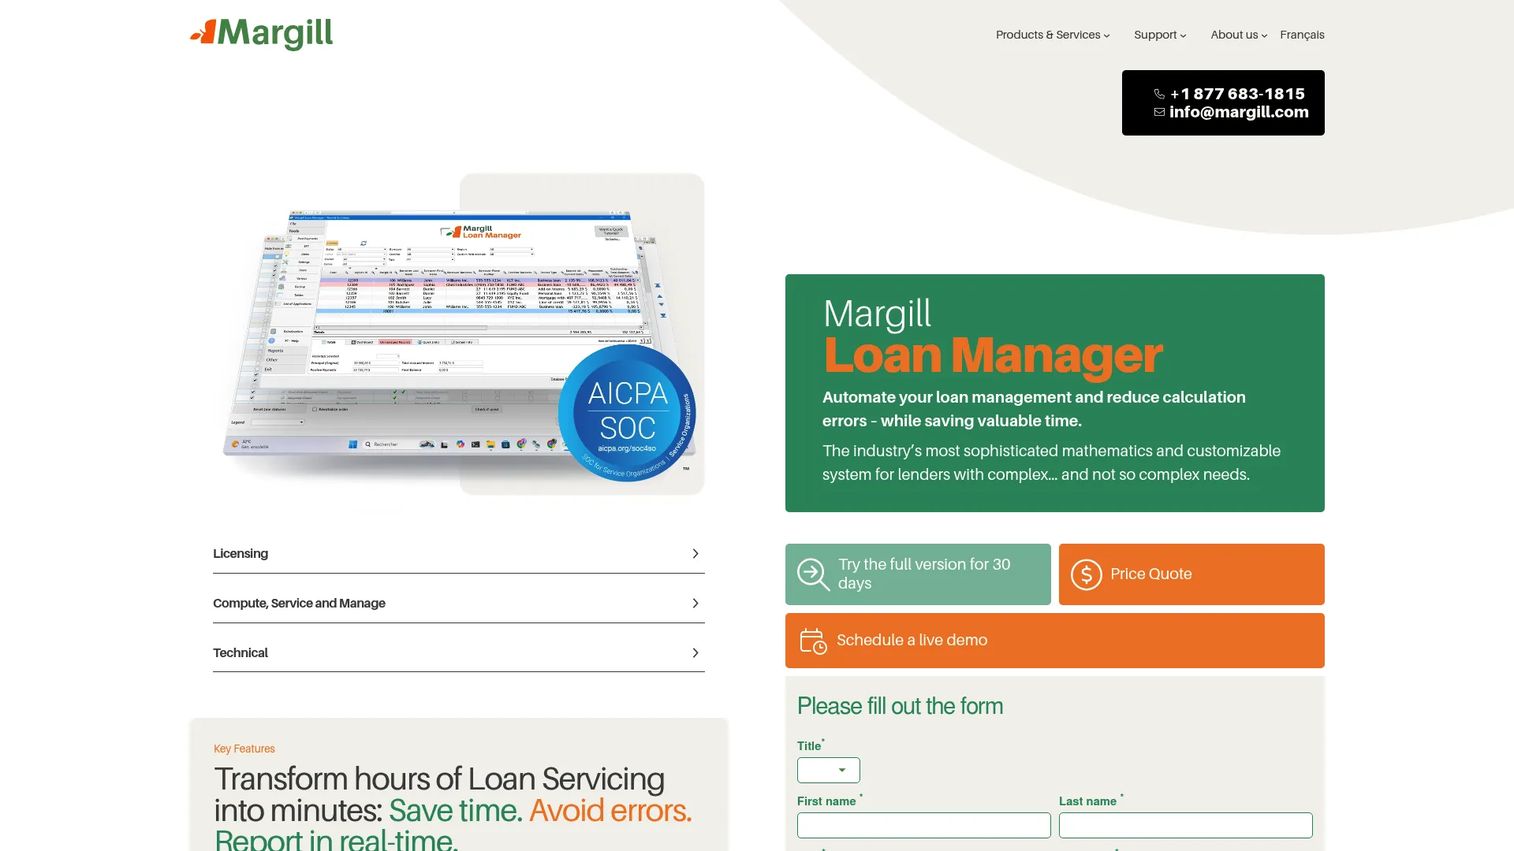
Margill Loan Manager is loan servicing and management software built for lenders managing complex or high-volume portfolios. Its strength is calculation flexibility: It handles simple and complex amortization schedules, fixed and variable interest rates, automated payment tracking, fees, EFT, and custom loan structures. It integrates with Salesforce, Sage, QuickBooks, and e-signature tools.
Best for: Private lenders and finance teams that need flexible loan calculations, amortization depth, and loan management without enterprise-level complexity.
Key features
- Loan origination and application importing
- Simple and complex amortization schedules
- Fixed and variable interest rate calculations
- Automated payment tracking, alerts, and EFT
- API and integrations with Salesforce and QuickBooks
Why choose Margill Loan Manager: Choose it when the problem is calculation flexibility and loan administration rather than institution-wide pricing strategy or regulatory documentation. It is a pragmatic fit for private lenders and finance teams that need reliable numbers without an enterprise rollout.
Margill Loan Manager pricing: Pricing is quote-based and depends on loan count and user count. A 30-day trial is available. Contact Margill directly for a quote.
G2 rating: 4.8/5 (verified on G2, based on 2 reviews)
10. defi SOLUTIONS
defi SOLUTIONS provides end-to-end loan and lease origination, servicing, and outsourced servicing software for auto and consumer finance lenders. It serves banks, credit unions, captive auto lenders, and consumer finance companies. Pricing in defi SOLUTIONS sits within the broader auto lending workflow: Origination parameters, credit policy rules, and dealer channel configuration all connect to how loans are structured and priced before funding.
Best for: Auto lenders that need pricing embedded in a full origination, servicing, and dealer channel platform.
Key features
- Loan and lease origination
- API-enabled loan and lease servicing
- Account, collateral, collections, and default management
- Digital self-service borrower portal
- Outsourced servicing with white-label customer care
Why choose defi SOLUTIONS: It fits auto lenders where pricing is inseparable from origination logic, dealer relationships, and servicing workflows. If your team needs a standalone pricing calculator, defi SOLUTIONS is more than required. If you need pricing connected to the full lending operation, it belongs on your shortlist.
defi SOLUTIONS pricing: Pricing requires a sales conversation. Contact defi SOLUTIONS or request a demo. Expect the quote to reflect modules, lending volume, implementation scope, and servicing requirements.
G2 rating: 5.0/5 (verified on G2, based on 2 reviews)
11. iSoftpull
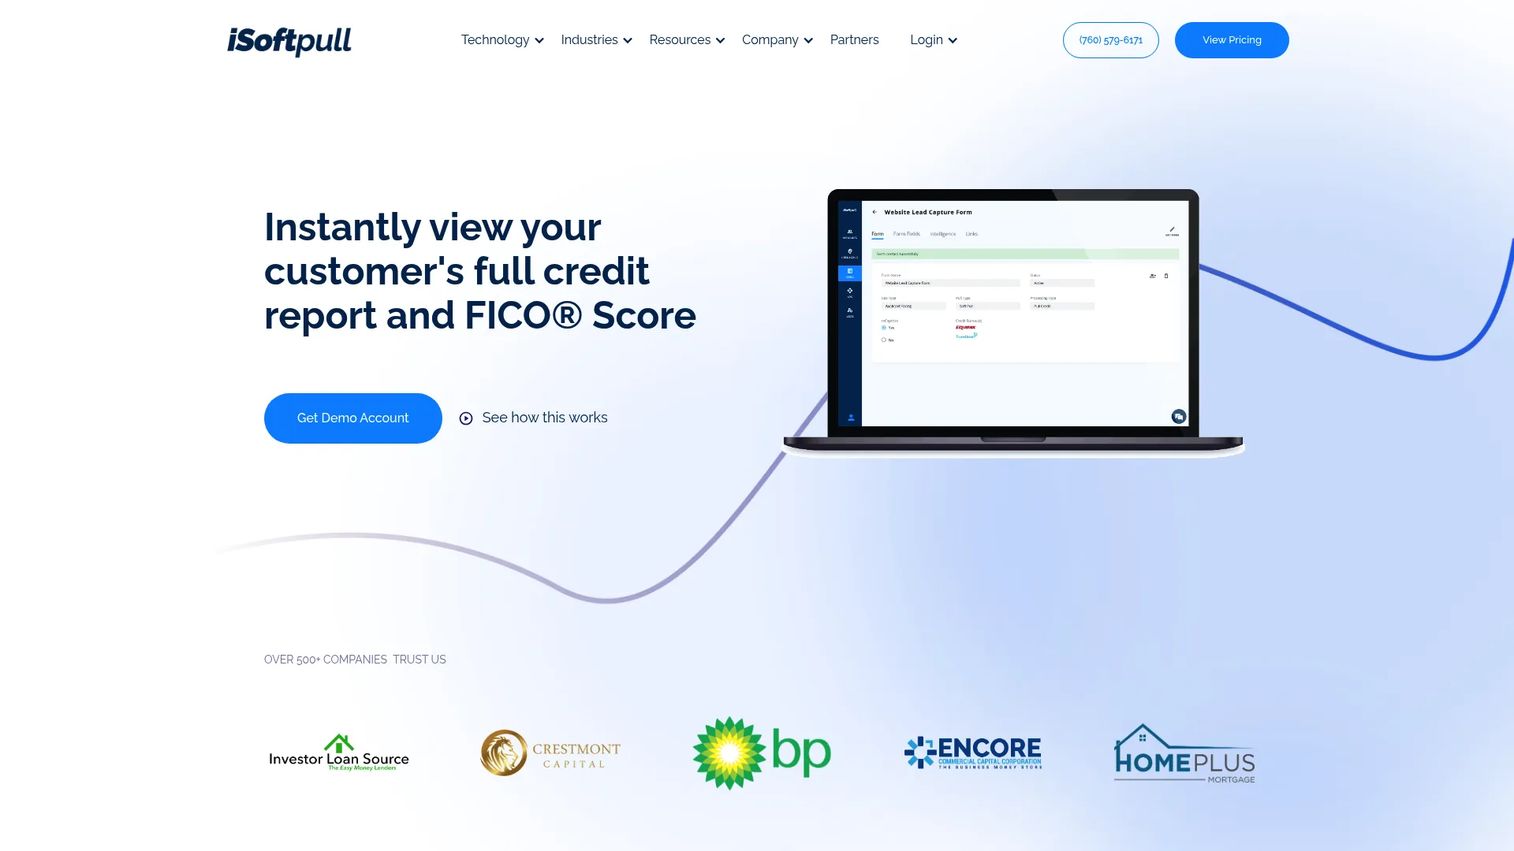
iSoftpull is credit reporting software that lets lenders pre-qualify borrowers using soft credit pulls, without a social security number and without affecting the applicant's credit score. It accesses Equifax, Experian, and TransUnion data, supports hard pulls for full underwriting, and offers embeddable credit webforms and API integrations. It is not a loan pricing platform. Its role is as an input layer feeding borrower risk data into prequalification and pricing workflows.
Best for: Lenders that need fast, soft-pull borrower credit data to support prequalification or risk-based pricing inputs before underwriting.
Key features
- Soft pulls without SSN or credit-score impact
- Full credit reports and FICO Scores
- Access to Equifax, Experian, and TransUnion data
- Embeddable credit webforms
- API and integration solutions
Why choose iSoftpull: It solves a specific problem: Getting borrower credit data early in the process without triggering a hard inquiry. Use it alongside a pricing platform to give the model accurate risk inputs before quoting a rate.
iSoftpull pricing: Plans start at $99/month. Credit pull pricing is $3.84 per bureau per pull, with volume discounts and no long-term contract requirement.
Considerations when choosing loan pricing software
Lending type fit
Separate the tools by the pricing problem they actually solve. A mortgage product and pricing engine handles investor eligibility and rate comparisons. A commercial profitability platform handles relationship ROE and risk-adjusted deal analysis. A consumer optimization tool handles price elasticity and segment-level personalization. Buying the wrong category creates a tool that does not map to the decision your team actually needs to make.
Pricing methodology
Ask every vendor what the model includes. Cost of funds, operating costs, credit risk, capital allocation, fees, relationship value, and target ROE should all be explicit inputs, not assumptions. The methodology matters more than the interface. Institutions that skip this question often discover the model excludes a cost component that distorts their profitability numbers.
Scenario modeling depth
Run two or three real deals through each vendor's model during evaluation. Change rate, term, fees, collateral category, and relationship assumptions. A tool that shows what drives the yield difference between scenarios is worth far more than one that only displays the final number.
Reporting and documentation
Evaluate what the platform produces for loan committees, examiners, board reporting, and lender coaching. The output needs to be explainable and auditable after a decision is made. Ask to see a sample committee report and an exception justification output before signing.
Implementation and data requirements
Map your core system feeds, CRM data, deposit data, credit data, rate sheets, and portfolio history before committing. The first 30 days will reveal whether the project is a software implementation or a data-modeling initiative. Teams that skip this mapping step often add 60 to 90 days to their go-live timeline.
Conclusion
The right loan pricing software is determined by the pricing decision your team needs to improve, not by feature count.
LoanPricingPRO and Abrigo are the strongest starting points for banks and credit unions that need commercial relationship profitability and risk-based pricing with documentation. Experian Loan Pricing Optimization fits consumer lenders using analytical models for portfolio-level optimization. PrecisionLender is the front-line coaching tool for commercial relationship managers.
For mortgage teams, Marksman offers clear entry-tier pricing at $400/month; PollyEx targets capital markets execution. Margill Loan Manager covers private lenders and finance teams that need calculation flexibility. defi SOLUTIONS is the right call when pricing connects to auto lending origination and dealer operations. iSoftpull feeds credit data into the pricing workflow rather than replacing a pricing platform.
Shortlist by lending type first. Then run two or three recent deals through each vendor's model before taking a sales call. That test will tell you more than any demo.
FAQs
Loan pricing software calculates risk-adjusted, profitable pricing for loans by incorporating borrower risk, cost of funds, capital requirements, institutional return targets, and relationship value. It replaces spreadsheet-based pricing with a consistent model that produces comparable outputs across every loan officer and lending scenario.
Banks, credit unions, commercial lenders, consumer lenders, mortgage lenders, auto lenders, and private lenders all use some form of loan pricing tool. Within those institutions, the primary users are CFOs, chief lending officers, credit risk leaders, relationship managers, and mortgage operations teams.
Loan origination software manages application intake, document collection, underwriting workflows, approvals, and closing. Loan pricing software focuses specifically on calculating a profitable, risk-adjusted price before or during the approval stage. Some platforms combine both, but they solve different problems in the lending process.
Risk-based pricing adjusts interest rates and loan terms based on the borrower's credit profile, collateral, risk grade, and the lender's expected return after accounting for cost of funds and operating expenses. Institutions should validate their risk-based pricing methodology with internal risk and compliance teams before deploying any model.
Banks should evaluate profitability modeling depth, relationship pricing capability across loans and deposits, risk grade integration, committee documentation outputs, compatibility with core system data feeds, lender-level performance reporting, and ROE or ROA target alignment. Implementation support and advisory services matter as much as the software itself for community banks with limited analytics staff.
Credit unions should focus on tools built for community financial institution scale with support for relationship pricing and straightforward implementation. LoanPricingPRO and Abrigo are the two strongest candidates based on current positioning. Evaluate both by running a sample portfolio through each vendor's model before making a final recommendation to your leadership team.
Mortgage pricing software, often called a product and pricing engine, focuses on mortgage rates, investor eligibility, lock workflows, and secondary market execution. Broader loan pricing software addresses commercial profitability modeling, consumer price optimization, or risk-based bank pricing. The two categories solve different problems for different lending teams.
Most enterprise and financial institution tools in this category sell by quote. Entry points where pricing is public include Marksman's Online Quoting tier at $400/month and iSoftpull starting at $99/month plus $3.84 per bureau pull. For commercial and consumer banking platforms, expect the quote to factor in modules selected, user count, loan volume, implementation services, advisory support, and data integration requirements.